Glossary Accounting
Debit note
Definition
A debit note increases the amount due on an earlier invoice; under GST a supplier issues it for undercharging, and buyers also use it for purchase returns.
Example
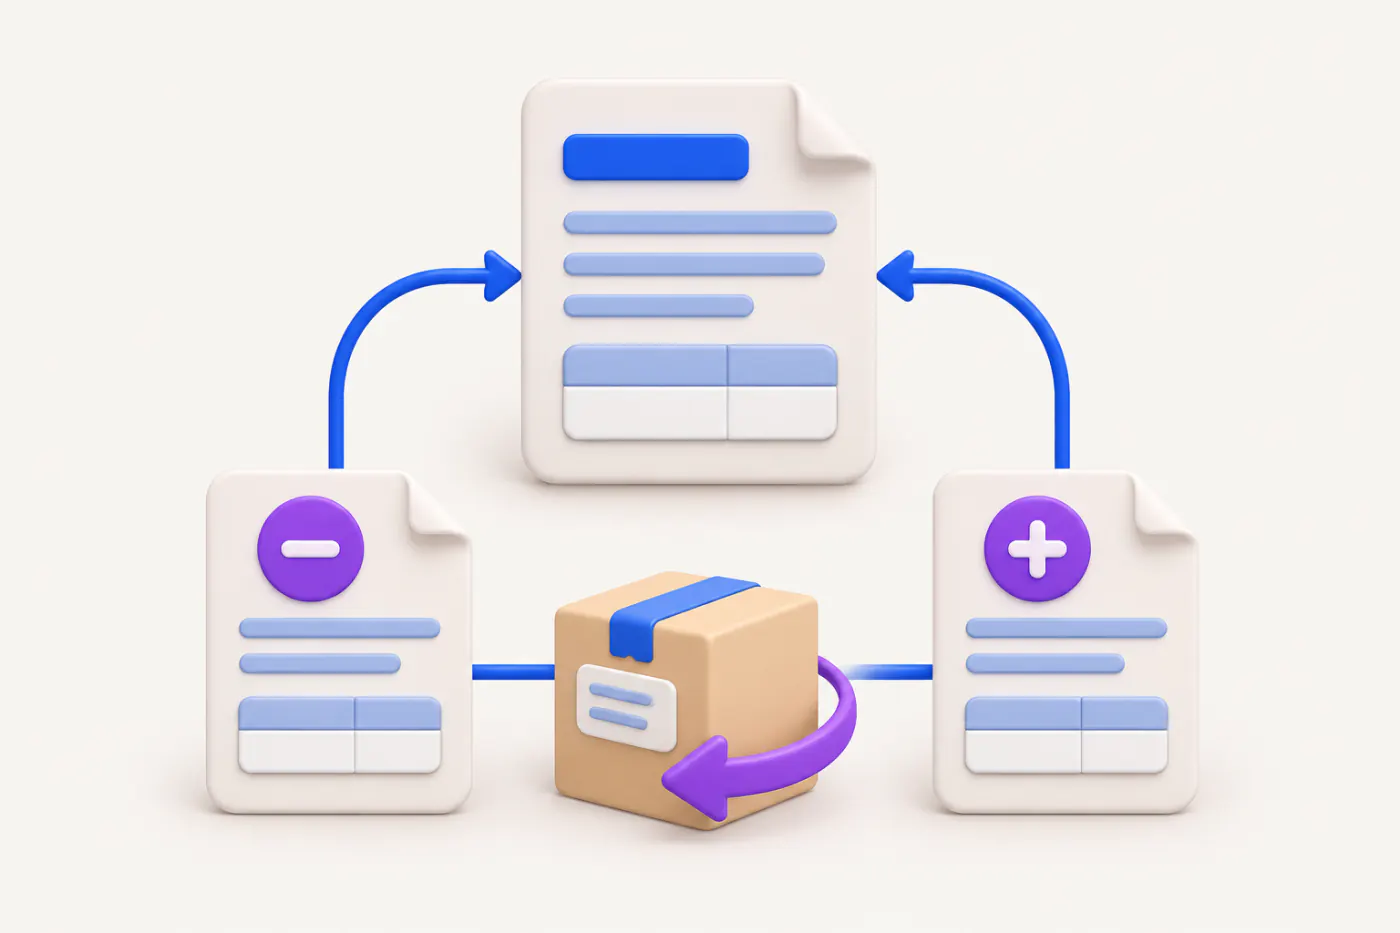
Khan Steel billed a buyer ₹2,00,000 for rods but the agreed price was ₹2,10,000. It issues a debit note for ₹10,000 plus ₹1,800 GST, ₹11,800 in all, quoting the invoice. Separately, when Mehta Paints returns ₹5,000 of damaged stock to its supplier, it records a debit note in its own books to reduce the payable.
Debit note in TallyPrime and in Cashflow OS
Where to find itIn TallyPrime
TallyPrime has a Debit Note voucher type, used for purchase returns (stock goes out) and for upward revisions of a sale. Link it to the original bill so bill-wise outstanding moves on the right bill.
 On your phoneIn Cashflow OS
Authorised users can create a debit note from the phone or web in Cashflow OS; the connector posts it into Tally, where Tally validates it.
See how it works
Common misunderstandings
- Watch outTreating a buyer's debit note as the GST document for a return. The supplier's credit note reduces the tax.
- Watch outLeaving out the original invoice reference, which the GST rules require on a supplier's debit note.
Two common uses
Under GST (issued by the supplier): when the taxable value or tax on an invoice was lower than it should be, for example a price increase applied after billing or a calculation error. The supplier issues a debit note with the extra amount and tax, refers to the original invoice, and reports it in GSTR-1. The buyer can claim credit on it subject to the usual conditions.
In accounting practice (issued by the buyer): when goods are returned to a supplier, many businesses raise a debit note to the supplier to reduce what they owe. For GST purposes, the supplier then issues the credit note. Both meanings are in common use, so read the document carefully.
Example
A steel trader billed 2 tonnes at ₹52,000 per tonne, ₹1,04,000 plus 18% GST. The agreed rate was ₹54,000. The trader issues a debit note for ₹4,000 plus ₹720 GST, ₹4,720 in all. The buyer's outstanding goes up by ₹4,720.
In the other case, a retailer returns ₹8,000 of goods (plus ₹1,440 GST) to its supplier and records a debit note in its own books, reducing the payable from ₹50,000 to ₹40,560, while it waits for the supplier's credit note. See our debit note format guide.
Where it shows up in TallyPrime
TallyPrime has a Debit Note voucher type used for purchase returns (it takes stock out) and for supplier-side increases to a customer's bill. Link it to the original bill reference so the bill-wise outstanding moves on the correct bill. Debit notes you issue as a supplier appear in GSTR-1. The difference between the two documents is covered in credit and debit notes in GST.
This is general information, not tax advice.
Related terms
Questions about Debit note
Is a debit note a bill?
Is there a time limit for a debit note?
Should I raise a debit note or ask for a credit note for returns?
Does a supplier's debit note go in GSTR-1?
Can the buyer claim ITC on a debit note?
This page is general information for Indian businesses, not tax, legal or financial advice. Rules and rates change — check the official portals or your CA before acting.