Invoices & documents Invoices
Revised invoice under GST
In GST law, a revised invoice has a narrow meaning: an invoice issued for sales made between the effective date of registration and the date the registration certificate is granted. Everyday corrections to a wrong invoice are handled with credit notes, debit notes or GSTR-1 amendments instead.
- Newly registered businesses
- Traders with backdated registration
- Billing and accounts staff
- Accountants handling corrections
- Owners fixing wrong invoices
On this page 11
The legal meaning
Sometimes registration is granted with effect from an earlier date. A trader who crossed the threshold and applied in time can get a certificate dated, say, 20 August, effective from 1 August. Sales between 1 and 20 August were billed without GST because the trader had no GSTIN yet.
Section 31(3)(a) of the CGST Act allows the registered person to issue revised tax invoices for those supplies within one month from the date the certificate is issued. Rule 53 of the CGST Rules sets out what the revised invoice must contain. This is the only document the law calls a revised invoice. This is general information, not tax advice.
Fields on a revised invoice
| Field | Example |
|---|---|
| Heading | Revised Invoice |
| Supplier name, address, GSTIN | Shiv Shakti Tiles, Morbi, 24ABCDE1234F1Z4 |
| Nature of document | Revised tax invoice |
| Serial number and date | RI/25-26/006, 15-09-2025 (up to 16 characters, unique in the year) |
| Recipient name, address, GSTIN | Kothari Ceramics, Rajkot, 24PQRSX5678K1Z9 |
| Original document number and date | Bill 118 dated 07-08-2025 |
| Taxable value, rate, tax | ₹1,20,000; CGST and SGST as applicable |
| Signature | Authorised signatory |
For supplies to unregistered buyers in this period, the rules allow a consolidated revised invoice in some cases, subject to conditions. Check the current rule on cbic-gst.gov.in before using it.
Worked example: registration backdated
Shiv Shakti Tiles' certificate is issued on 20 August, effective 1 August. Between 1 and 19 August it made three sales on plain bills.
| Original bill | Buyer | Amount charged | Revised invoice |
|---|---|---|---|
| 118, 7 Aug | Kothari Ceramics (registered) | ₹1,20,000 | RI/006 with GST shown |
| 121, 12 Aug | Patel Builders (registered) | ₹2,40,000 | RI/007 with GST shown |
| 124, 18 Aug | Walk-in consumer | ₹18,000 | Covered as allowed for unregistered buyers |
Whether the original amounts are treated as inclusive of tax, or the buyers pay tax on top, is a commercial question to settle with each buyer. Revised invoices must be issued by 19 September, one month after the certificate. Registered buyers can then claim credit on the revised invoices.
What people usually mean by a revised invoice
In daily use, revised invoice means we got something wrong and sent a corrected bill. Under GST, once a tax invoice is issued, you cannot simply replace it with a new one carrying the same number. Use the right tool:
| Problem | Correct route |
|---|---|
| Charged too much, or goods returned | Credit note |
| Charged too little | Debit note |
| Wrong GSTIN, wrong place of supply, wrong B2B/B2C type, already reported | Amend in a later GSTR-1 |
| Wrong in every way, not yet reported | Cancel and issue a new invoice with a new number |
See cancelling an invoice for the not-yet-reported case.
Why the replace-the-bill habit is risky
- Two documents with the same number exist, one in your books and one in the buyer's file.
- GSTR-1 shows the old values while the buyer's books show the new ones, so credit does not match.
- During scrutiny or audit, the trail from order to invoice to payment breaks.
If you must reissue for a printing error that does not change any value or detail, such as a smudged copy, write duplicate copy on it rather than calling it revised.
Checklist
- Is this a backdated-registration case? Then use a revised invoice within one month of the certificate.
- Otherwise, has the invoice been reported? Use a credit note, debit note or amendment.
- Not reported? Cancel and reissue with a fresh number.
- Inform the buyer in writing so both ledgers change together.
- Keep the original, the correction and the reason together.
Doing this with Tally and Cashflow OS
Corrections in TallyPrime are made with credit note and debit note vouchers or by altering a voucher before it is reported. With Cashflow OS, authorised users can create or alter vouchers, including credit and debit notes, from the phone through the connector, and Tally validates each one. The GSTR-1 view in Cashflow OS, prepared from Tally data, helps you spot rows that need amendment before filing. See GST reports.
Avoid these
Common mistakes
- MistakeReissuing a corrected bill with the same numberDo this instead
Keep the original and correct it with a credit note, debit note or GSTR-1 amendment, so your books, the return and the buyer's file agree.
- MistakeCalling every correction a revised invoiceDo this instead
Use the term only for the backdated-registration case; for other errors, pick the right route from the correction table.
- MistakeMissing the one-month window after registrationDo this instead
Note the date the certificate is issued and send revised invoices for the gap period well within one month.
- MistakeCorrecting the bill without telling the buyerDo this instead
Send the credit or debit note with a short written message, so both ledgers change together and the buyer's credit matches.
Keep handy
Checklist
Revised invoice under GST — 7 checks. Tick them as you go.
In Cashflow OS
How Cashflow OS helps
Cashflow OS puts your TallyPrime books on every phone in the team. Where it fits this topic:
Credit and debit notes from the phone
With writing into Tally switched on, authorised users can create or alter vouchers, including credit and debit notes, from the app, and Tally validates each one.
See Create Tally vouchers from your phone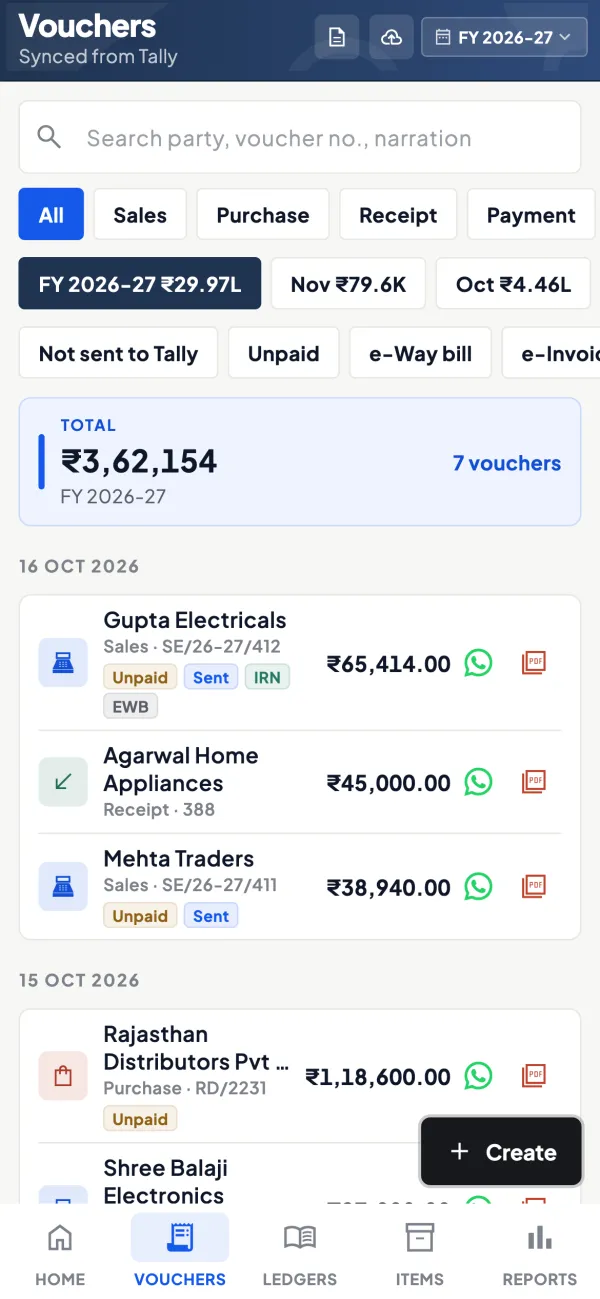
Spot rows that need amendment
The GSTR-1 view prepared from Tally data opens bill-wise detail, so a wrong GSTIN or value can be caught before you file on the portal.
See GST reports from your Tally data
Questions people ask
Is a revised invoice the same as an amended invoice?
What is the time limit for issuing revised invoices?
Can I issue a revised invoice for a price change?
Does a revised invoice need its own series?
Can a revised invoice be issued for sales to unregistered buyers?
Should I cancel an invoice that has a wrong amount?
Is a duplicate copy the same as a revised invoice?
Do revised invoices go into GSTR-1?
This page is general information for Indian businesses, not tax, legal or financial advice. Rules and rates change — check the official portals or your CA before acting.